E-Way Bill New Rules 2026: What Changed and What It Means for Shippers
Key Highlights
- GSTN kept the ship-to GSTIN mandate and the e-way bill closure facility on hold via its advisory dated 29 July 2026.
- GSTN has suspended the Ship-To GSTIN mandate and closure facility as of July 2026.
- Enforcement now focuses on 180-day document limits and 360-day extension caps.
- E-way bill generation reached the second-highest monthly level on record in July 2026.
The 2026 E-Way Bill Rulebook Sits on the 2025 Baseline, Not a Fresh Overhaul
E-way bill requirements are generally governed by the applicable provisions of the CGST Act, 2017, and CGST Rules, 2017, including provisions relating to when an e-way bill may be required and the information it should contain.
What actually changed in 2026 was announcement traffic, not law. GSTN issued a series of advisories proposing two portal-level enhancements, deferred them once, and then put them on hold entirely. Meanwhile, the validations introduced in January 2025 kept running quietly in the background, blocking generation attempts every day across the country.
That distinction matters for anyone planning a compliance project. The e-way bill rules you have to satisfy on the loading dock tomorrow morning are the same ones you were satisfying in December, enforced more strictly and with far less tolerance for stale documentation.
The Two Proposed 2026 Changes and Their Current Hold Status
The first made the ship-to GSTIN a compulsory field in bill-to/ship-to transactions. The second introduced a voluntary closure facility, letting a supplier, recipient, transporter, or driver mark an e-way bill as delivered rather than leaving it open until its validity lapsed.
The timeline is worth knowing because vendor communication on it has been inconsistent. GSTN first flagged the changes in advisories issued in May 2026, targeting a 15 June rollout. After representations from ERP vendors, GSPs, and ASPs, the date moved to 1 August 2026.
Then, on 29 July 2026, GSTN issued an advisory placing the proposed enhancements on hold until further notice, withdrawing the related advisories and FAQs from the portal, and instructing taxpayers not to modify their systems based on the earlier guidance.
So no field on the GST e-way bill portal became mandatory on 1 August. Software that started enforcing Ship-To GSTIN client-side ahead of the deadline may now be blocking invoices that the portal itself would accept, which is worth checking with your vendor this week.
What the Ship-To GSTIN Requirement Would Change for Bill-To/Ship-To Dispatches
The proposal itself was straightforward, and the direction of travel has not changed even if the date has. Under the drafted rules, the delivery-location GSTIN would have to be captured separately during e-waybill generation, with the value URP entered where the consignee is unregistered.
Two operational consequences follow. First, your customer and consignee masters need to hold verified GSTINs for delivery locations, not just billing entities, and for most manufacturers, that data has never been maintained to that standard.
Second, dispatch teams would need a decision rule for when a movement genuinely qualifies as Bill-To/Ship-To, since goods sent to a buyer's own additional place of business under the same GSTIN were to be treated as an ordinary transaction rather than a three-party one.
Master data cleanup is worth continuing regardless of the hold. It carries no compliance risk, it improves invoice accuracy today, and it converts the eventual go-live from a project into a configuration change.
E-Way Bill Applicability and Generation Rules Still Governing Every Dispatch in 2026
These are the rules currently being enforced, and they are where penalties actually originate.
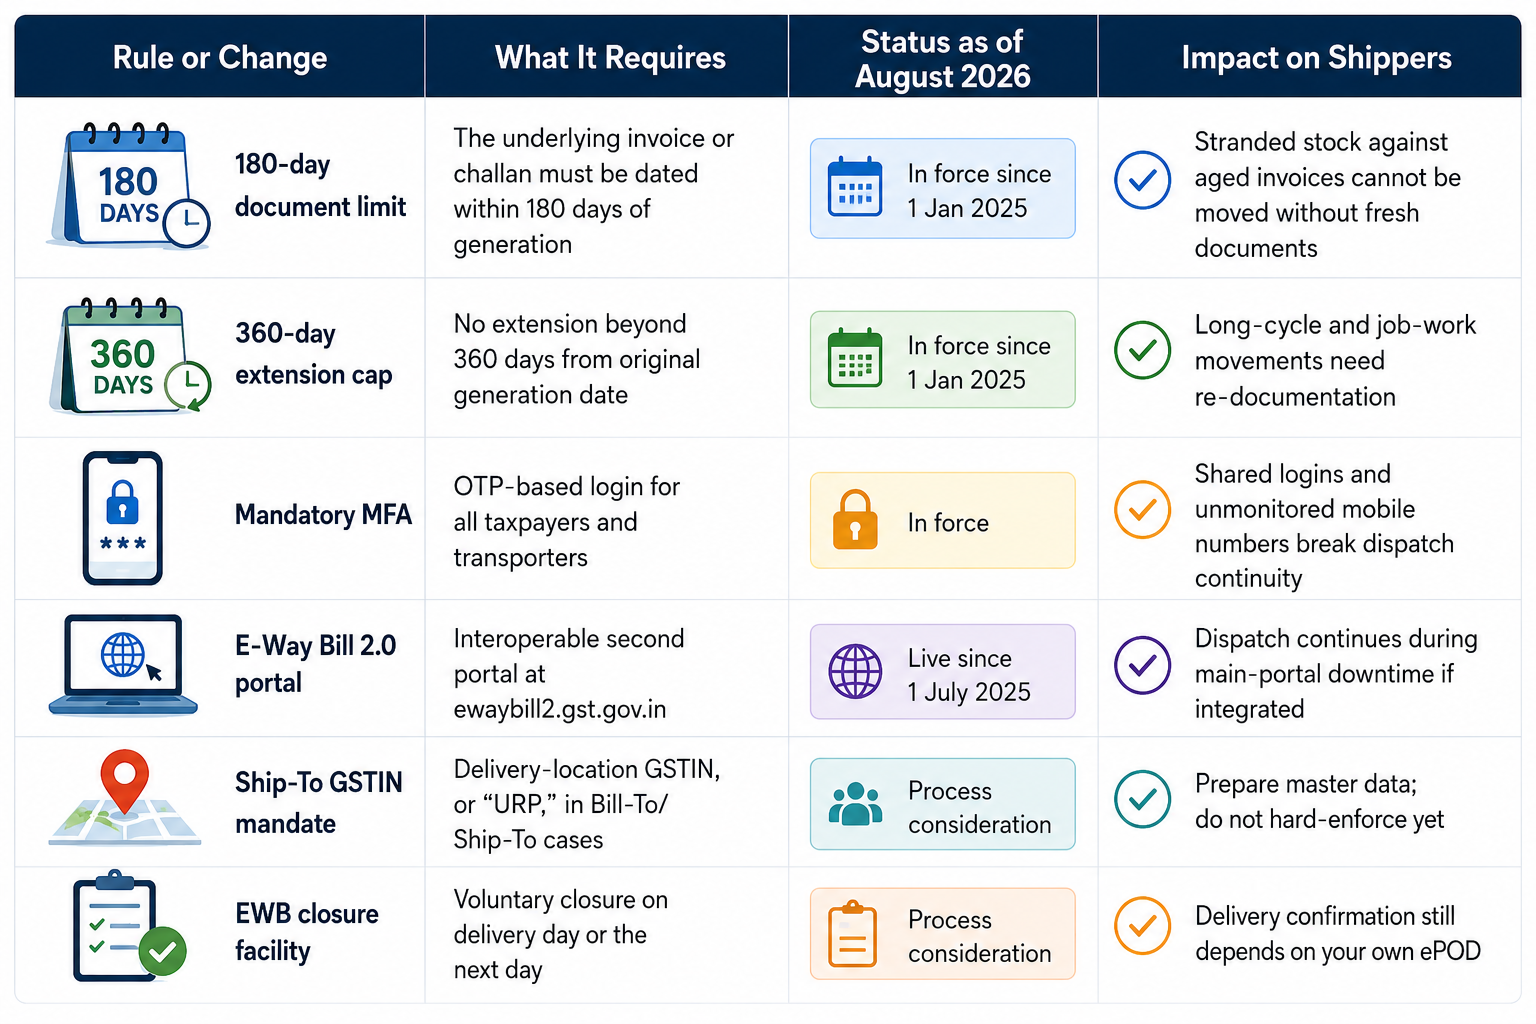
Also note that e-waybill registration remains a prerequisite for unregistered transporters, who obtain a transporter ID to operate on the system. Generation continues to work online, through APIs, or via SMS, and Part B entry still starts the validity clock.
What Are the Primary E-Way Bill Risks Shippers Face in 2026?
It is an e-way bill that expires while the truck is still moving. Validity runs at one day per 200 km for regular cargo, and a breakdown, a detention at a checkpoint, or a delayed unloading slot can push a consignment past expiry before anyone in the control tower notices.
Detention consequences are severe under Section 129 of the CGST Act, and they land on goods that are already in motion, which means the cost is rarely just the penalty. It is the stalled vehicle, the missed delivery window, the customer escalation, and the invoice that cannot be raised.
The second risk is reconciliation. With the closure facility deferred, bills stay open in the system after delivery, and matching movement records against dispatch data (reconciliation) remains a manual exercise, directly impacting Days Sales Outstanding (DSO) for shippers.
RoaDo’s hardware-free freight operating system addresses this by combining DPI integrations (GSTN and VAHAN) with proactive exception alerts. With proactive exception alerts, flagging bills approaching expiry while a shipment is still in transit rather than after the fact, an approach that has helped users avoid over 1 lakh delays.
How Can Manufacturers Prepare for the Next Wave of E-Way Bill Changes?
Treat the hold as time bought, not time off. GSTN has signaled its architectural direction clearly across three advisories this year, and the eventual notification will come with a short runway.
Start with consignee master data: validate delivery-location GSTINs across your top customers and mark unregistered destinations for URP handling. Ask your ERP or GSP vendor two specific questions: whether their schema already carries a separate Ship-To GSTIN field and whether any client-side mandatory validation was switched on before 1 August that now needs reversing.
Assign one person to check the News and Updates section of the GST portal weekly, since a fresh advisory is the only warning you will get.
Then look at the exception layer. Expiry alerts, delay flags, and delivery confirmation are where compliance failures actually surface, and they need to run against live shipment status rather than a spreadsheet reviewed at day's end.
RoaDo’s hardware-free platform links dispatch data to compliance status, removing the manual monitoring step without requiring any GPS hardware or driver apps.
Conclusion
Much of the noise around e-way bill changes this year came from proposals that were announced, rescheduled, and ultimately suspended, leaving many teams prepared for a deadline that never arrived. The rules that genuinely govern dispatch today are the 2025 validations, and they are being enforced with far more consistency than before.
The practical risk for shippers is not a missed advisory but an expired bill on a moving truck, a stale invoice that blocks generation, or an open record no one reconciled. Clean consignee master data, a live view of shipment status, and an exception workflow that fires before expiry will handle both today's enforcement and whatever GSTN eventually notifies.
Platforms like RoaDo are built for exactly this kind of lifecycle-level complexity, and the direction of regulation makes that capability harder to postpone with each passing quarter.
Frequently Asked Questions
1. Did the e-way bill rules change recently?
GSTN has kept the proposed Ship-To GSTIN requirement and e-way bill closure facility on hold. The existing e-way bill requirements continue to apply.
2. Is Ship-To GSTIN mandatory for e-way bills?
Not currently. The Ship-To GSTIN requirement was proposed for Bill-To/Ship-To transactions but has been kept on hold until further notice.
3. When is an e-way bill required?
An e-way bill is required for applicable movements of goods under the prevailing GST rules. The exact requirement can depend on factors such as the type of movement, goods involved, and applicable exemptions.
4. Can an e-way bill be generated using an old invoice?
The underlying invoice or document must meet the applicable validity requirements. If the document falls outside the permitted period, fresh documentation may be needed before generation.
5. How long does an e-way bill remain valid?
Validity depends mainly on the distance to be covered and the type of goods being transported. Extensions may be available in eligible circumstances under the applicable rules.
6. Can a delivered e-way bill be closed manually?
The proposed voluntary closure facility has been kept on hold. Businesses therefore continue to rely on their existing delivery confirmation and reconciliation processes.
7. What is the E-Way Bill 2.0 portal used for?
The E-Way Bill 2.0 portal is intended to support continued e-way bill operations during system downtime, with interoperability between the relevant portals.
8. Is multi-factor authentication required for the e-way bill portal? Multi-factor authentication forms part of the e-way bill portal's security requirements for applicable users. Businesses should keep user access and registered mobile details updated.
“RoaDo helps shippers stay ahead of e-way bill compliance with automated monitoring, real-time alerts, and seamless GSTN integration without adding manual work."